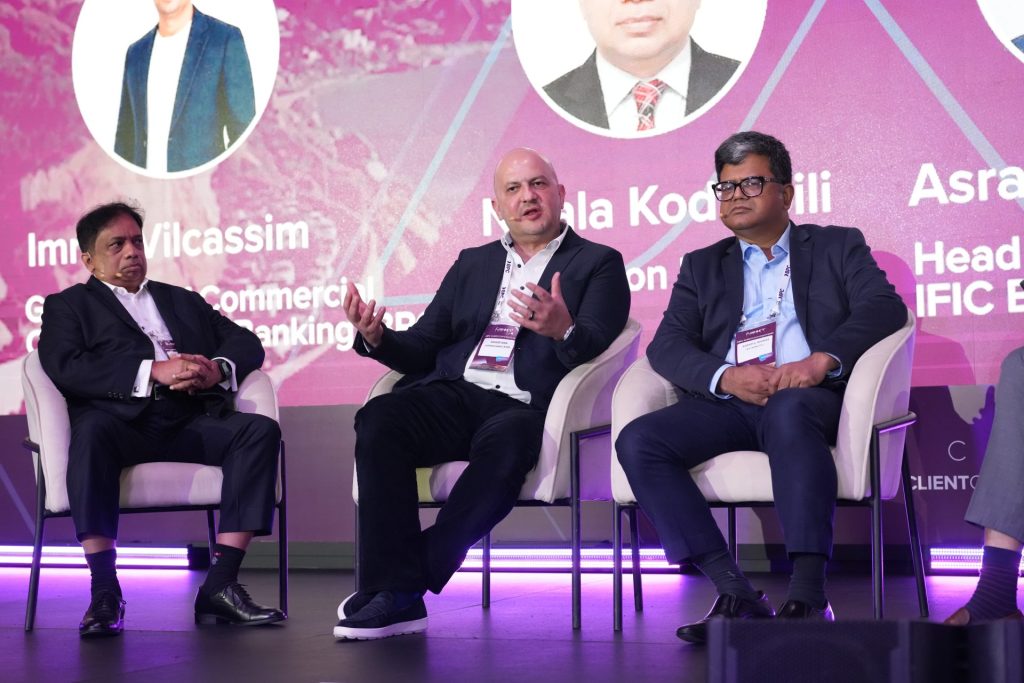
Pic : Speakers unpacking a number of topics at the BPC Conference in Cape Town
By Lwazi Raul Shongwe
As financial technologies expand and digital transactions become integral to global commerce, the fight against digital financial fraud, identity theft, and cybercrime has never been more vital. Speaking at the BPC Client Conference 2026 , experts and delegates explored actionable insights drawn from real-world payment transformation initiatives, highlighting pivotal insights shared by the State Bank of Vietnam on securing modern payment infrastructure.
To establish a resilient, secure, and future-proof digital payment ecosystem, financial institutions, regulatory authorities, and technology providers must collaborate across four core pillars:
Identity is the Foundation
The cornerstone of any secure financial network is robust, verifiable identity verification. Reliable customer identification and authentication systems provide the essential groundwork necessary to prevent identity-related fraud, synthetic account creation, and unauthorized account access. Implementing strong Know Your Customer (KYC) and biometric authentication standards ensure trust at every transaction touchpoint.
Data Sharing Creates Collective Strength
Operating in isolation limits an organization’s view of threat vectors. By sharing risk intelligence and threat data across the ecosystem, financial institutions can identify suspicious entities and fraudulent networks that extend far beyond their internal datasets. Collective data exchange empowers the broader market to spot cross-platform attacks in real time.
Inter-Agency Coordination is Essential
Preventing sophisticated financial crime requires a unified front. Seamless coordination among financial regulators, law enforcement agencies, commercial banks, and payment service providers drastically strengthens prevention efforts, speeds up criminal investigations, and improves fund-tracing capabilities across jurisdictions.
Preventive Measures Must Continuously Adapt
Fraud tactics are constantly evolving alongside technological advancements. Fraud risk controls cannot remain static; they must continuously adapt to emerging threats while maintaining a seamless user experience that protects legitimate customers and transactions. Harnessing AI-driven anomaly detection and adaptive security protocols ensures protection without hindering economic activity.
Looking Ahead
The experience shared by the State Bank of Vietnam highlights that building a safe payment ecosystem is not solely a technical challenge, but an ecosystem-wide responsibility. As global organizations leverage solutions from pioneers like BPC, implementing robust identity foundations, cross-sector intelligence sharing, multi-agency collaboration, and adaptive security measures will be crucial to safeguarding the future of global digital commerce.